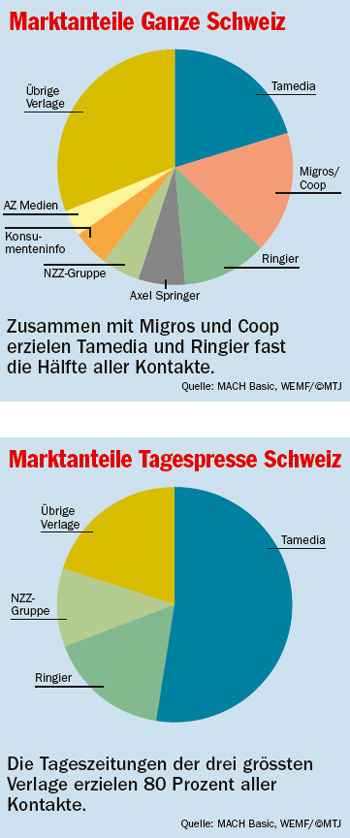
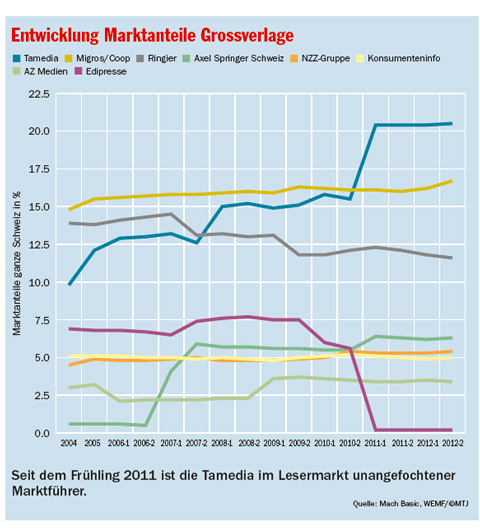
If the reader market is defined as the sum of all contacts of the titles covered by the MTJ (see box "Basic information" on page 3), the concentration in the Swiss publishing industry can be seen very clearly. While the media houses listed in the chart "Development of market shares of major publishers" still accounted for 58.5 percent of all contacts in 2004, this figure has now risen to 69.3 percent. There have been five winners and three losers since 2004. The winners are Tamedia, Axel Springer Switzerland, the major distributors, the NZZ Group and AZ Medien. The development at Tamedia outshines everything else. Thanks to an aggressive acquisition strategy (20 Minuten, Espace Media, Edipresse) and new launches (20 Minuten in western and southern Switzerland), it has more than doubled its market share from 9.8 to 20.5 percent and has been the clear market leader since spring 2011.
Tamedia damages Ringier
The main relative winner in the long-term comparison is Axel Springer Switzerland, which has increased its market share more than tenfold through the takeover of the former Jean Frey AG and Ringier's German-language TV program titles, moving up from last place to fourth. Since 2004, the two major distributors Coop and Migros have gained 1.9 points to 16.7 percent, also gaining 0.7 points on the previous year. Ringier's market share, on the other hand, has fallen by 2.4 percentage points compared to 2004. This was mainly due to the sale of the program titles to Axel Springer and the discontinuation of Cash and Gesundheit - Sprechstunde. A slight loss of 0.6 points was recorded compared to the previous year. On the one hand, the significant losses of Schweizer Illustrierte, Illustré and Glückspost contributed to this. However, almost half of this was due to TV täglich, which is published as a joint venture with Tamedia. For this reason, the readership figures are attributed equally to the two publishers. The piquant thing is that the readers were lost because Tamedia no longer includes the program supplement in its two major daily newspapers in German-speaking Switzerland. However, as Tamedia's total contacts have only decreased in line with the overall market, it has been much less affected by this measure.
The NZZ Group continues to hold fifth place with a market share of 5.4% in Switzerland as a whole, ahead of Konsumenteninfo, which was able to maintain its share of 5.0% despite significant losses of its titles K-Tipp and Bon à savoir. AZ Medien was also able to maintain its market share of 3.4% compared to the previous year - despite a significant loss of the AZ Gesamtausgabe. The current situation is shown in the chart "Market shares for the whole of Switzerland".
Tamedia dominates everywhere
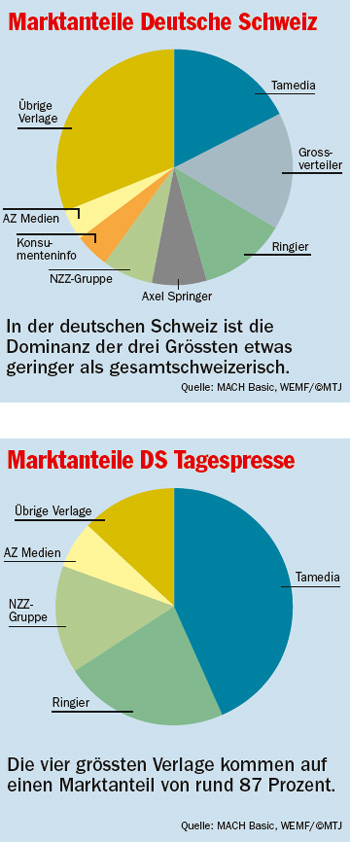
In German-speaking Switzerland, Tamedia is one point ahead of the two major distributors with a market share of 17.2 percent. Ringier is slightly stronger than in Switzerland as a whole, while Axel Springer achieves 1.4 percentage points more in German-speaking Switzerland than in Switzerland as a whole. This is because the subsidiary of the major German publisher is only represented in French-speaking Switzerland by the niche title PME Magazine. The NZZ Group and AZ Medien operate exclusively in German-speaking Switzerland. Both therefore score higher here than in Switzerland as a whole. In German-speaking Switzerland, AZ Medien is 0.5 points behind Konsumenteninfo with 4.3 percent, while the NZZ Group is significantly better off with a constant 6.7 percent. The other publishers have a market share of around 31% both nationwide and in German-speaking Switzerland.
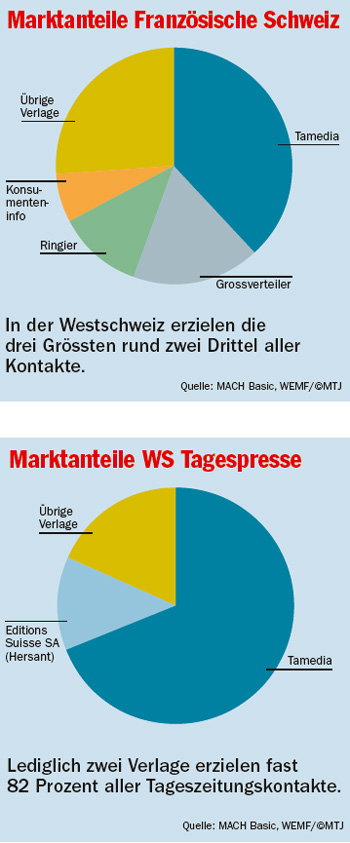
In French-speaking Switzerland, however, the other publishers only hold a good quarter of the reader market. With 38.2 percent, Tamedia is as dominant there as the now fully integrated Edipresse was. Konsumenteninfo also has the strongest position here with 6.7 percent. Ringier, on the other hand, holds around 12 percent in both major language regions, while the major distributors are 1.3 points stronger in French-speaking Switzerland than in German-speaking Switzerland with 17.5 percent.
Concentrated daily press
If we focus on the daily newspapers that are published at least four times a week, Tamedia's dominance becomes even greater. In Switzerland as a whole, its titles generate more than half of all daily newspaper contacts, in German-speaking Switzerland a comparatively modest 43 percent. In French-speaking Switzerland, on the other hand, 69 percent of all contacts come from the three paid daily newspapers and one free daily newspaper distributed by Tamedia Publications Romand. The rest of the market is shared by Editions Suisse SA, the subsidiary of the French newspaper group Hersant, with just under 13 percent and the other publishers with around 18 percent. In German-speaking Switzerland, four publishers share 87 percent of the reader market. Ringier has the second-highest market share with just under 23 percent. And this with just two titles, Blick and Blick am Abend. The three daily newspapers of the NZZ Group (NZZ, St. Galler Tagblatt and Neue Luzerner Zeitung) together account for 15 percent of all daily newspaper contacts.
Just as in German-speaking Switzerland, the three major publishers have a market share of around 80 percent in the daily press market throughout Switzerland. This may seem threatening at first glance. However, as the various titles of Tamedia and the NZZ Group can work very independently in editorial terms, this concentration in the opinion market only poses a certain threat in individual cases, such as with topics from the media market.
The situation is somewhat different at Ringier, where the content of the two Blick titles comes from the same newsroom and therefore hardly represent diametrically different positions.
Ueli Custer